 Facebook
 X
 Pinterest
 Copy Link
Understanding Fixtures vs. Non-Fixtures in Real Estate: What Stays and What Goes
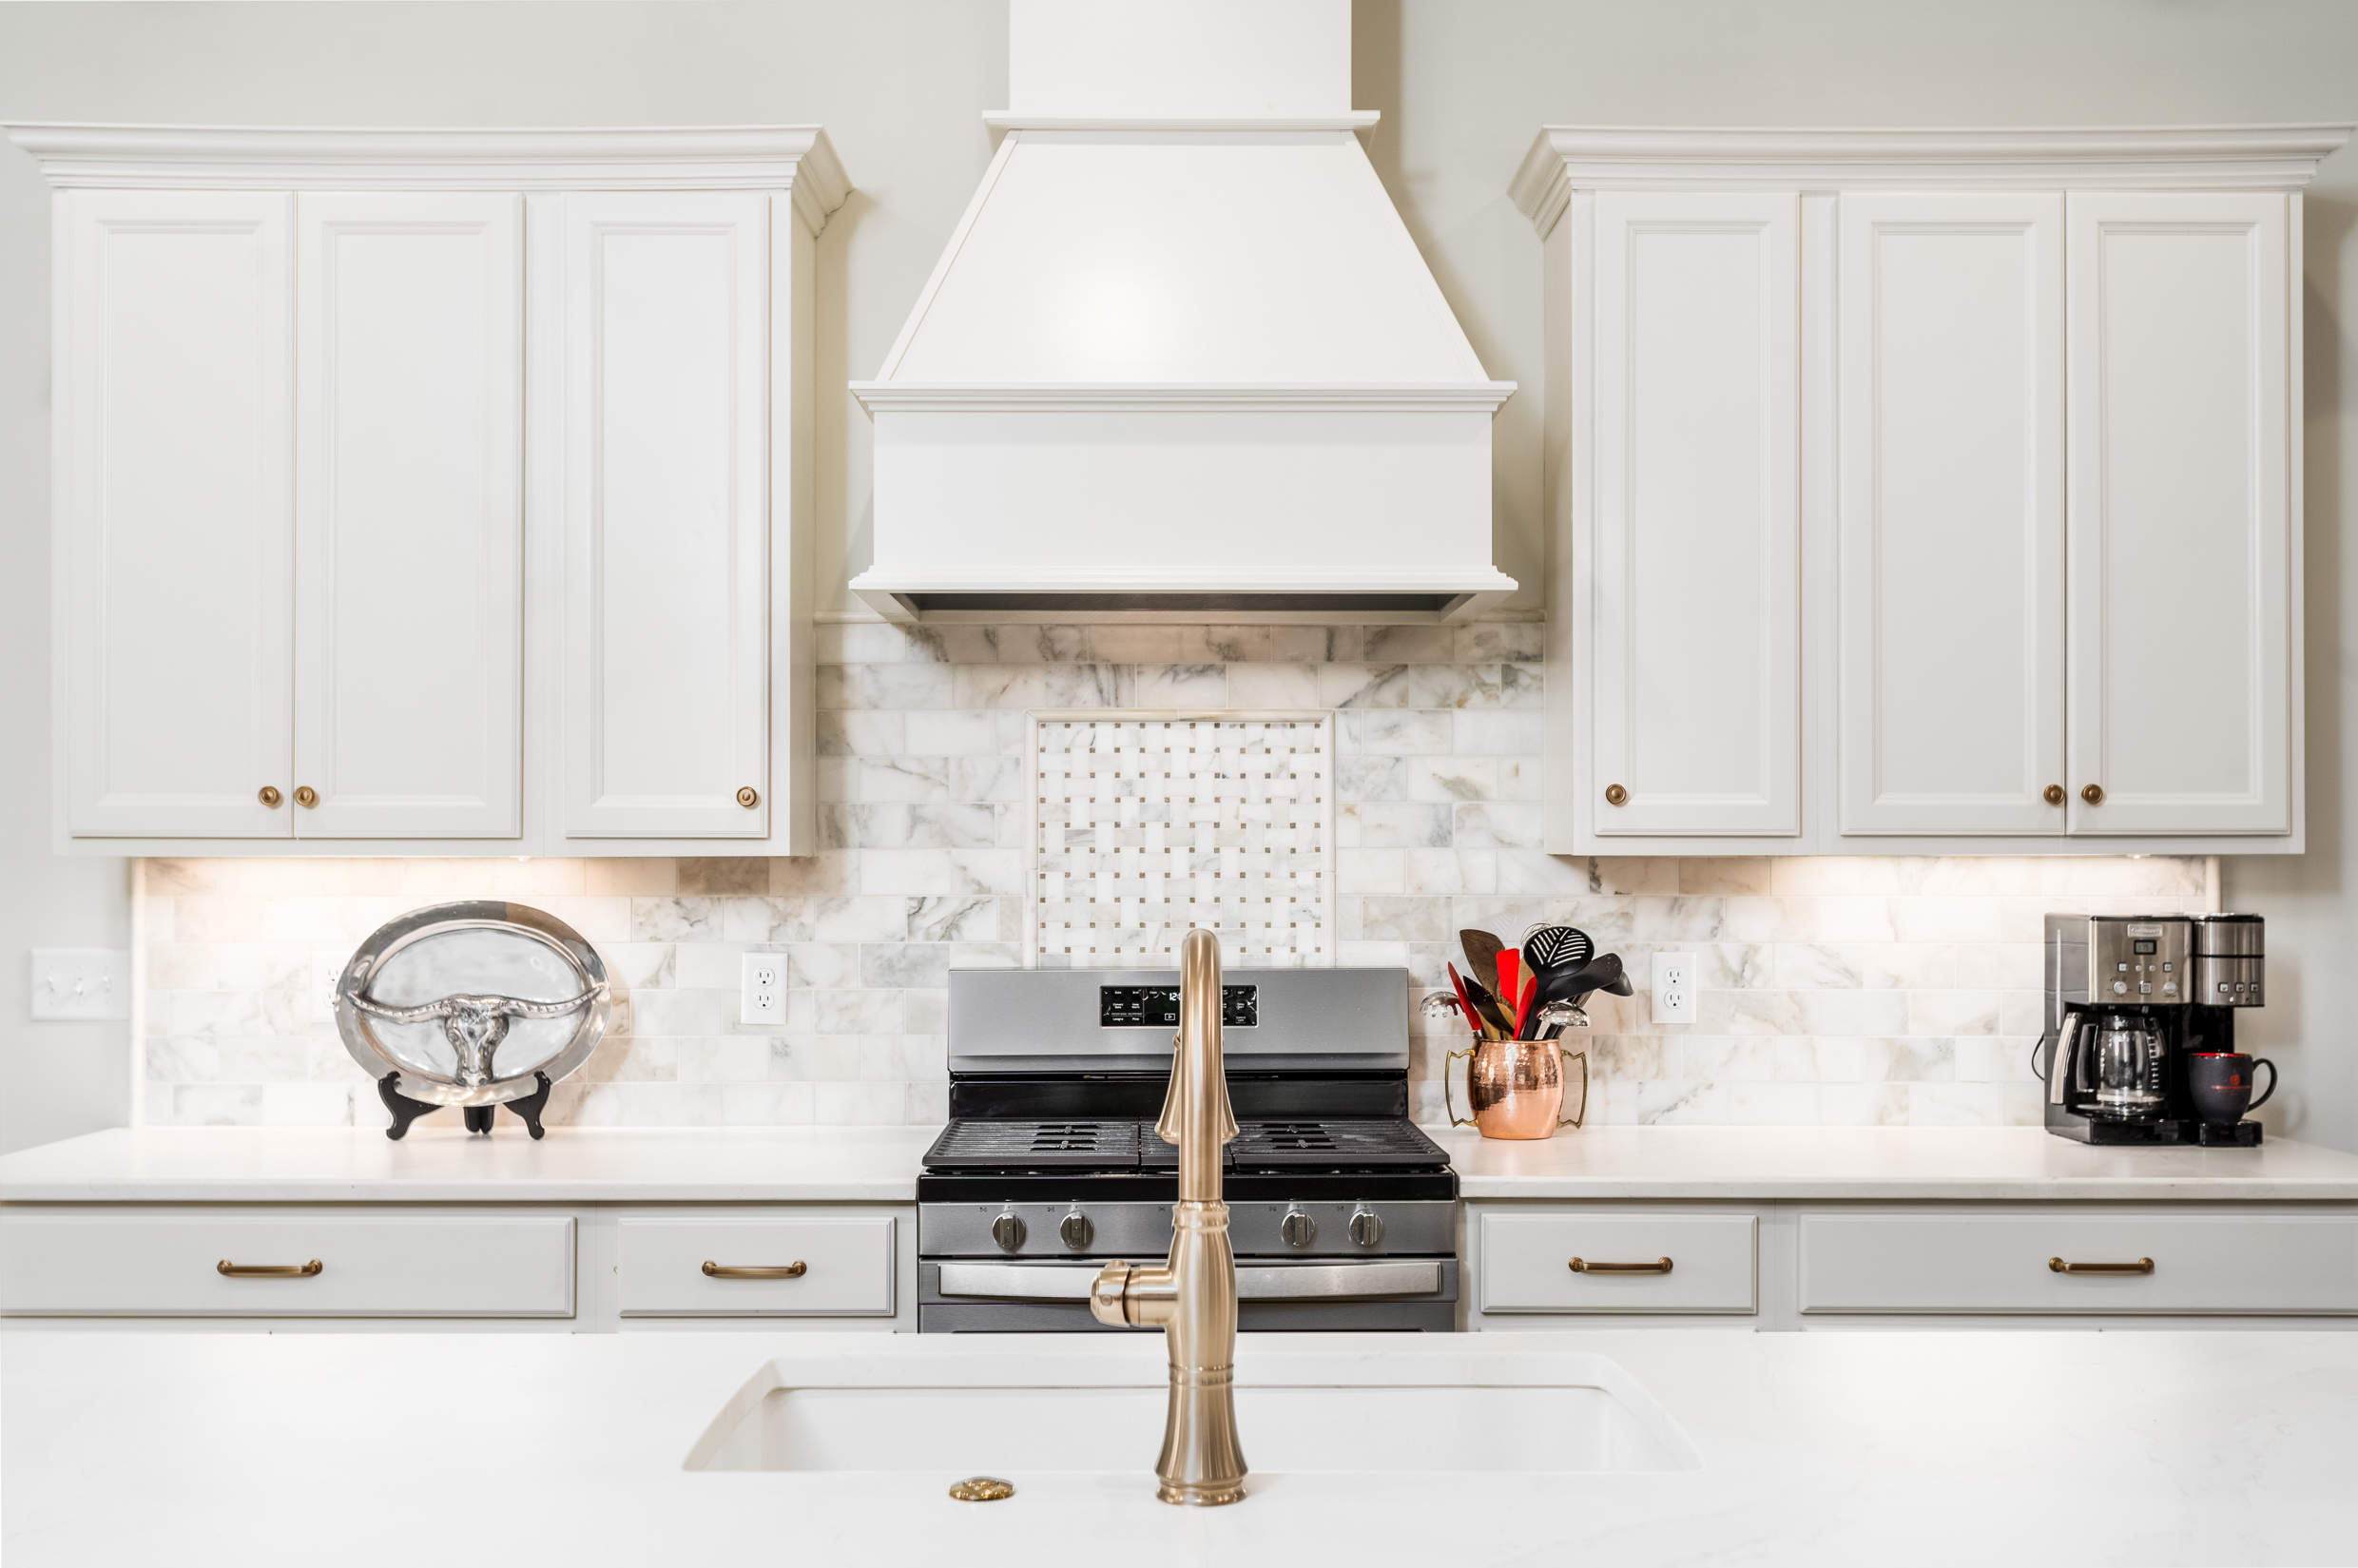
When you purchase a new home, it’s essential to understand the distinction between fixtures and non-fixtures. Fixtures are items that are considered part of the property and typically stay with the house when it changes ownership. Non-fixtures, on the other hand, are items that are not permanently attached and are not included in the sale. Let’s delve into examples of both to shed light on why these distinctions matter in real estate transactions.
Fixtures:
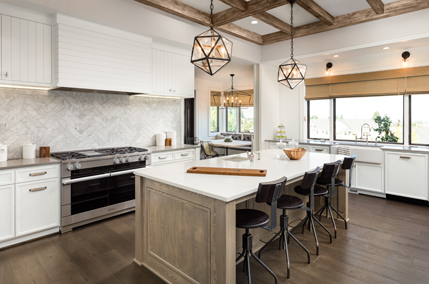
- Built-In Appliances: Built-in kitchen appliances such as ovens, dishwashers, and stovetops are considered fixtures. They are usually attached to the property and are expected to remain with the home when you buy it.
- Light Fixtures: Permanent light fixtures, like chandeliers and ceiling fans, are fixtures. They are typically installed and meant to be part of the property.
- Window Treatments: In many cases, blinds and curtains that are custom-fitted to windows may be considered fixtures and stay with the house. However, curtains and drapes are considered personal property and need to be negotiated in the contract if the buyer would like to keep them.
- Landscaping: Trees, shrubs, and plants that are part of the landscape design are fixtures. However, potted plants or removable garden decorations are not.


Non-Fixtures:
- Furniture and Personal Belongings: Items like sofas, dining tables, and personal belongings are non-fixtures. They are not permanently attached and do not come with the house.
- Portable Appliances: Appliances like a refrigerator, washer, dryer, or standalone microwave are non-fixtures and are typically not included in the sale unless specified otherwise.
- Rugs and Carpets: While wall-to-wall carpeting may be considered a fixture, area rugs are not. They can be easily removed and taken by the seller.
- Wall Art and Decorations: Paintings, mirrors, and wall decorations are non-fixtures. They are personal items and are not part of the property’s structure.


The reason behind these distinctions is to provide clarity in real estate transactions and avoid disputes between buyers and sellers. Fixtures are considered part of the property’s value, and buyers expect them to remain in place. Non-fixtures, on the other hand, are the seller’s personal property and are not included unless specifically negotiated.
It’s crucial to review the list of fixtures and non-fixtures in the purchase agreement to ensure that both parties are on the same page. If there are items that the buyer wishes to include or exclude, it should be clearly documented in the contract. Understanding these distinctions helps ensure a smooth transition when buying or selling a home and prevents any surprises along the way.
Understanding Contingencies in Real Estate Contracts
Understanding Contingencies in Real Estate Contracts
In the world of real estate, contingencies are like safety nets, providing protection and flexibility for both buyers and sellers. These contractual clauses are essential for ensuring that a real estate transaction proceeds smoothly, allowing buyers to secure their dream home and sellers to move forward with confidence. In this blog post, we’ll explore the different types of contingencies commonly found in real estate contracts, including those contingent on the sale of property, financial contingencies, contingencies based on inspections, and contingencies dependent on appraisals.

Property Sale Contingency:
One of the most common contingencies in real estate contracts is the “contingent on the sale of property” clause. This contingency allows a buyer to make an offer on a new property while still trying to sell their existing one. It provides buyers with the flexibility to pursue a new home without the financial burden of owning two properties simultaneously.
For instance, imagine you’re a homeowner looking to upgrade to a larger house. You find the perfect home, but you can’t afford it unless you sell your current property. In this case, you can include a contingent on the sale of property clause in your offer. If you can’t sell your home within a specified timeframe, the contract becomes void, protecting you from financial strain.
Financial Contingency:
Financial contingencies are crucial for buyers who need to secure financing to purchase a property. This contingency ensures that the buyer is not obligated to complete the purchase if they can’t obtain the necessary financing. It protects the buyer from potential financial hardship and allows them to withdraw from the contract without penalties.
Let’s say you’re a buyer who needs a mortgage to buy your dream home. A financial contingency gives you the option to back out of the deal if your loan application is denied or the terms of the loan are unfavorable. This contingency also sets a timeline for securing financing, adding a level of certainty to the transaction.

Inspection Contingency:
Contingencies based on property inspections are designed to protect the buyer’s interests by allowing them to assess the condition of the property. These inspections typically cover aspects like the structure, plumbing, electrical systems, and pest infestations. If the inspection reveals significant issues that the seller is unwilling to address or negotiate on, the buyer can back out of the contract without forfeiting their earnest money.
For instance, during a home inspection, you discover a major roof leak or a serious foundation problem. Thanks to the inspection contingency, you can either ask the seller to make the necessary repairs or terminate the contract if an agreement cannot be reached.
Appraisal Contingency:
A contingent on appraisal clause is another important element in real estate contracts. It protects both buyers and lenders by ensuring that the property’s appraised value matches or exceeds the purchase price. If the appraisal comes in lower than the agreed-upon price, the buyer can renegotiate with the seller, request a lower purchase price, or withdraw from the contract.
Suppose you’ve agreed to purchase a home for $300,000, but the appraisal values it at only $280,000. With a contingent on appraisal clause, you have options: you can renegotiate with the seller to lower the price, pay the difference out of pocket, or withdraw from the deal if an agreement cannot be reached.
In conclusion, contingencies in real estate contracts are essential safeguards that protect both buyers and sellers, providing flexibility and peace of mind throughout the transaction process. It’s important to note that virtually anything can be made into a contingency as long as it is explicitly detailed in the contract and agreed upon by both parties. These contractual clauses, whether contingent on the sale of property, financial contingencies, contingent on inspection, or contingent on appraisal, are designed to ensure that real estate transactions are fair, transparent, and mutually beneficial. When entering into a real estate contract, it’s crucial to work with a knowledgeable real estate agent or attorney who can help you navigate the intricacies of contingencies, tailor them to your specific needs, and ensure that your interests are protected every step of the way.